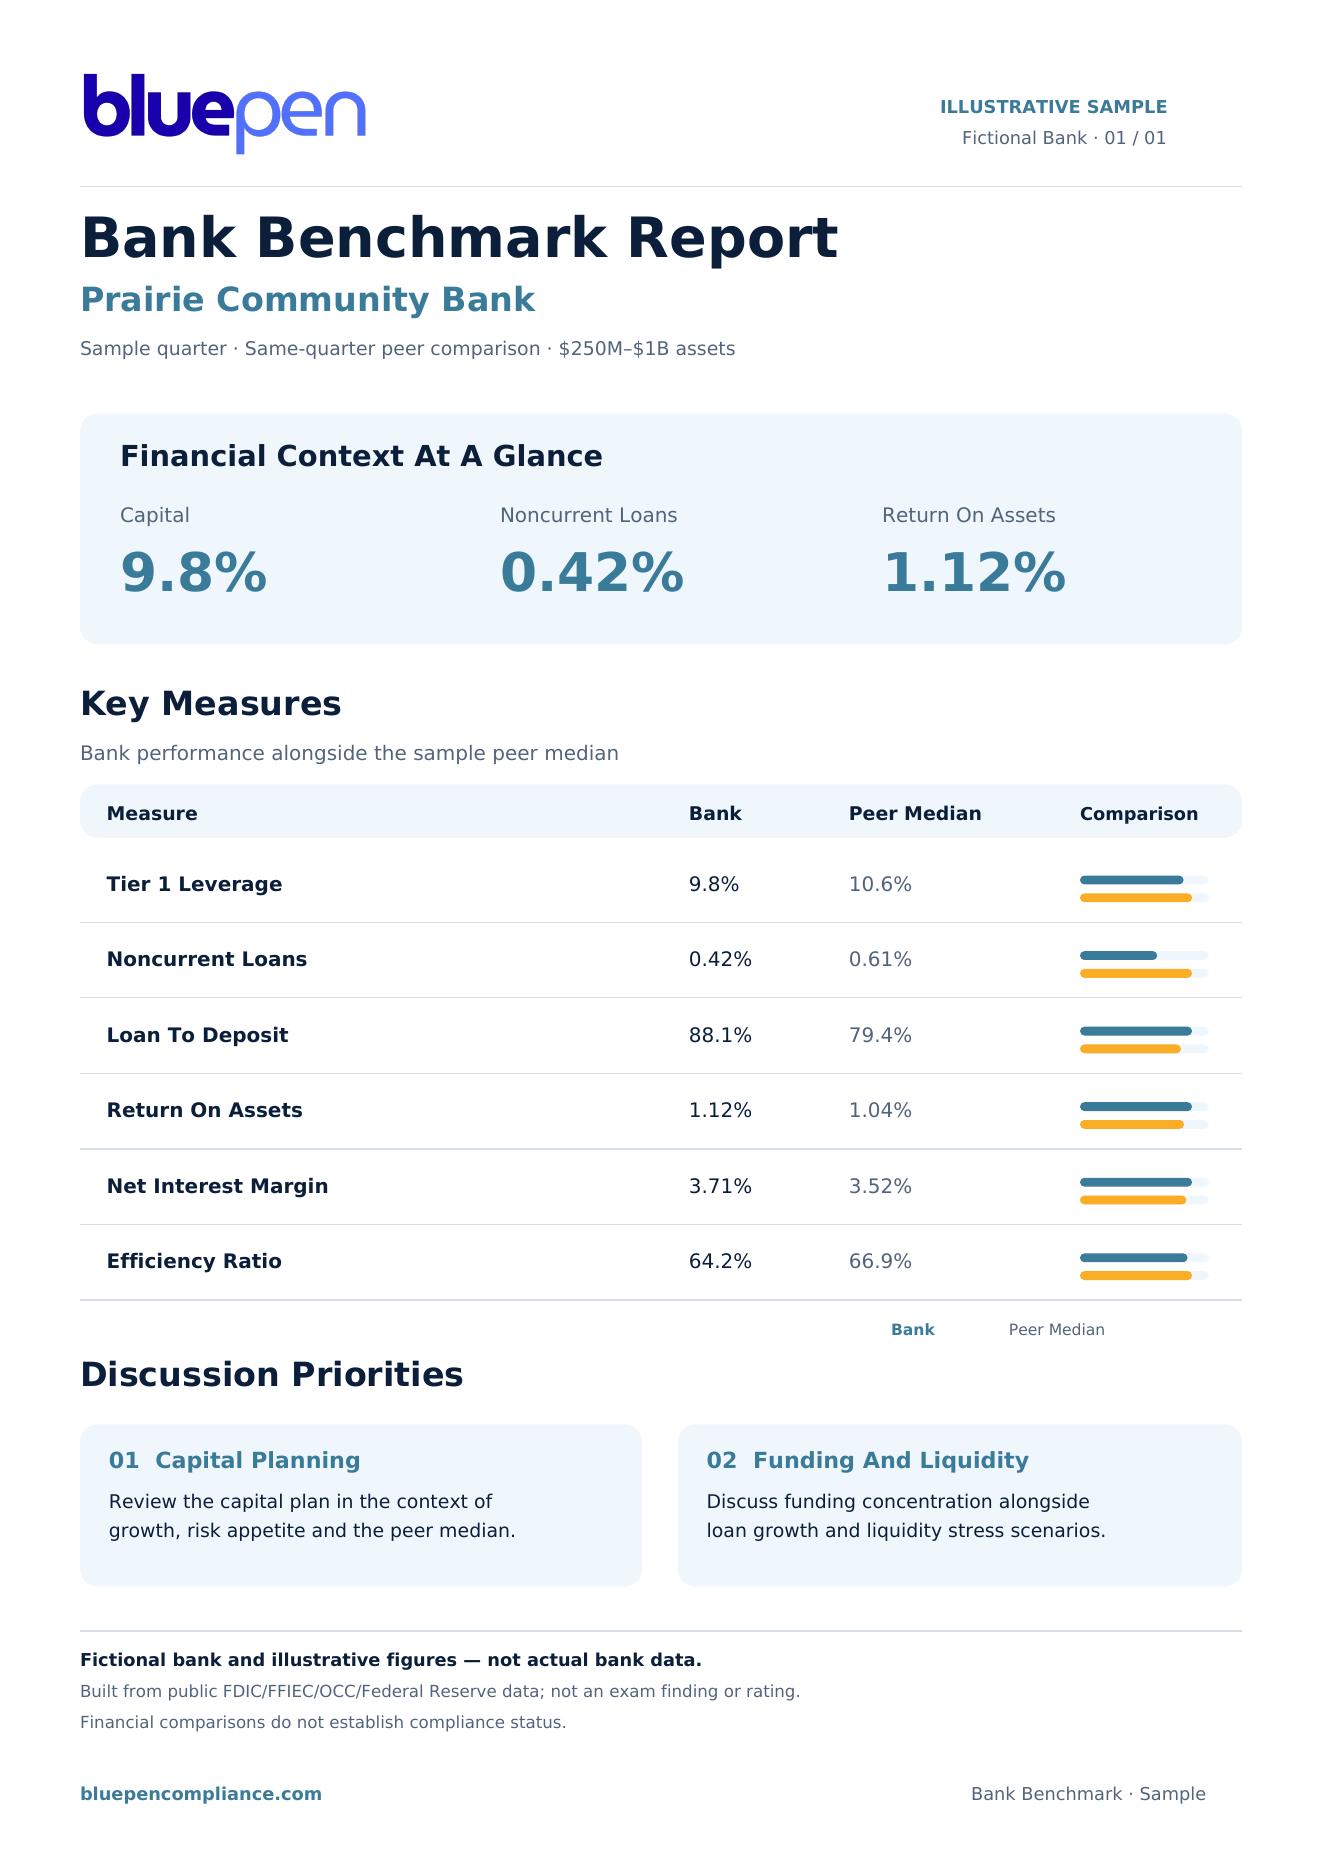
Prairie Community Bank
Sample report
Sample peer group: State nonmember banks · $250M–$1B assets · Oklahoma · 24 peers
54
of 100
2
Strengths
3
Watch
1
Flags
Sample Peer Banks (24)
Fictional names for illustration. Real reports list the actual peer banks.
- Peer Bank A
- Peer Bank B
- Peer Bank C
- Peer Bank D
- Peer Bank E
- Peer Bank F
- and 18 more
Tier 1 Leverage
Bank 9.8% · Peer median 10.6%
Peer range 8.1% – 14.2%
38th percentile among peers
Noncurrent Loans
Bank 0.42% · Peer median 0.61%
Peer range 0.05% – 2.31%
72nd percentile among peers
Loan To Deposit
Bank 88.1% · Peer median 79.4%
Peer range 52.3% – 101.6%
31st percentile among peers
Return On Assets
Bank 1.12% · Peer median 1.04%
Peer range 0.31% – 1.88%
58th percentile among peers
Net Interest Margin
Bank 3.71% · Peer median 3.52%
Peer range 2.64% – 4.45%
63rd percentile among peers
Efficiency Ratio
Bank 64.2% · Peer median 66.9%
Peer range 48.7% – 88.2%
61st percentile among peers
CRA Rating Vs Peer Rating Mix
Sample bank: Satisfactory
- Outstanding4
- Satisfactory19
- Needs to Improve1
- Substantial Noncompliance0
Outstanding Vs Satisfactory Peers
Sample peer group: 4 rated Outstanding, 19 rated Satisfactory.
| Measure | Outstanding Peers | Satisfactory Peers | This Bank | What To Do To Move Up |
|---|---|---|---|---|
| Lending TestLoan-to-deposit ratioSource: FFIEC Call Report (via FDIC BankFind) | 84% | 76% | 71% | Lift lending relative to deposits by expanding local loan programs or participations, and document reasons if the ratio stays below peers. |
| Lending TestShare of lending inside the assessment areaSource: FFIEC CRA and HMDA disclosure data | 85% | 72% | 68% | Track loans by geography each quarter and steer outreach so a clear majority of loans stay inside the assessment area. |
| Lending TestLending to low/moderate-income borrowers and geographiesSource: FFIEC CRA and HMDA disclosure data | Above demographics | Near demographics | Below demographics | Compare your borrower and tract mix with census and aggregate lender data, then set targets and outreach for LMI borrowers and tracts. |
| Lending TestSmall business/farm lendingSource: FFIEC CRA and HMDA disclosure data | Strong share to small businesses/farms | Reasonable share | Limited share | Add small-dollar business and farm products and record revenue data so loans to businesses under $1 million can be counted. |
| Investment TestQualified investments and donations (share of assets/capital)Source: Public CRA performance evaluations | Significant level | Adequate level | Limited level | Set an annual budget for qualified investments such as LMI-targeted bonds, CDFI deposits and affordable-housing funds, and keep documentation. |
| Service TestBranches in LMI areasSource: Public CRA performance evaluations | Readily accessible | Reasonably accessible | Few LMI locations | Map branches and ATMs against LMI tracts; review hours and consider a branch, ATM or mobile service where access is thin. |
| Service TestCommunity development service hoursSource: Public CRA performance evaluations | Leadership roles | Regular participation | Few documented hours | Log staff hours on financial education and nonprofit boards that serve LMI people, with dates and the community purpose. |
| Service TestAlternative delivery systemsSource: Public CRA performance evaluations | Shown effective for LMI use | Available | Not documented | Show how online, mobile and low-cost accounts reach LMI customers, using usage data where possible. |
| Community DevelopmentCommunity development loansSource: Public CRA performance evaluations | Leader in the area | Adequate level | Few loans | Identify affordable-housing, small-business and revitalization projects in the area and record them as community development loans. |
| InnovationInnovative/flexible productsSource: Public CRA performance evaluations | Several flexible programs | Some flexibility | None noted | Offer flexible underwriting such as lower down payments, credit-builder loans or special-purpose credit programs, and track results. |
Lending Test
Loan-to-deposit ratio
- Outstanding Peers
- 84%
- Satisfactory Peers
- 76%
- This Bank
- 71%
What To Do To Move Up: Lift lending relative to deposits by expanding local loan programs or participations, and document reasons if the ratio stays below peers.
Source: FFIEC Call Report (via FDIC BankFind)Lending Test
Share of lending inside the assessment area
- Outstanding Peers
- 85%
- Satisfactory Peers
- 72%
- This Bank
- 68%
What To Do To Move Up: Track loans by geography each quarter and steer outreach so a clear majority of loans stay inside the assessment area.
Source: FFIEC CRA and HMDA disclosure dataLending Test
Lending to low/moderate-income borrowers and geographies
- Outstanding Peers
- Above demographics
- Satisfactory Peers
- Near demographics
- This Bank
- Below demographics
What To Do To Move Up: Compare your borrower and tract mix with census and aggregate lender data, then set targets and outreach for LMI borrowers and tracts.
Source: FFIEC CRA and HMDA disclosure dataLending Test
Small business/farm lending
- Outstanding Peers
- Strong share to small businesses/farms
- Satisfactory Peers
- Reasonable share
- This Bank
- Limited share
What To Do To Move Up: Add small-dollar business and farm products and record revenue data so loans to businesses under $1 million can be counted.
Source: FFIEC CRA and HMDA disclosure dataInvestment Test
Qualified investments and donations (share of assets/capital)
- Outstanding Peers
- Significant level
- Satisfactory Peers
- Adequate level
- This Bank
- Limited level
What To Do To Move Up: Set an annual budget for qualified investments such as LMI-targeted bonds, CDFI deposits and affordable-housing funds, and keep documentation.
Source: Public CRA performance evaluationsService Test
Branches in LMI areas
- Outstanding Peers
- Readily accessible
- Satisfactory Peers
- Reasonably accessible
- This Bank
- Few LMI locations
What To Do To Move Up: Map branches and ATMs against LMI tracts; review hours and consider a branch, ATM or mobile service where access is thin.
Source: Public CRA performance evaluationsService Test
Community development service hours
- Outstanding Peers
- Leadership roles
- Satisfactory Peers
- Regular participation
- This Bank
- Few documented hours
What To Do To Move Up: Log staff hours on financial education and nonprofit boards that serve LMI people, with dates and the community purpose.
Source: Public CRA performance evaluationsService Test
Alternative delivery systems
- Outstanding Peers
- Shown effective for LMI use
- Satisfactory Peers
- Available
- This Bank
- Not documented
What To Do To Move Up: Show how online, mobile and low-cost accounts reach LMI customers, using usage data where possible.
Source: Public CRA performance evaluationsCommunity Development
Community development loans
- Outstanding Peers
- Leader in the area
- Satisfactory Peers
- Adequate level
- This Bank
- Few loans
What To Do To Move Up: Identify affordable-housing, small-business and revitalization projects in the area and record them as community development loans.
Source: Public CRA performance evaluationsInnovation
Innovative/flexible products
- Outstanding Peers
- Several flexible programs
- Satisfactory Peers
- Some flexibility
- This Bank
- None noted
What To Do To Move Up: Offer flexible underwriting such as lower down payments, credit-builder loans or special-purpose credit programs, and track results.
Source: Public CRA performance evaluations
Sample values are illustrative only and do not describe a real bank.
What Outstanding Banks Do Differently
- Lend a clear majority of loans inside the assessment area, with an LMI borrower and tract mix at or above demographics.
- Make community development loans and qualified investments a planned, budgeted program rather than occasional activity.
- Keep branches, ATMs and digital services accessible in LMI areas and document how LMI customers use them.
- Have staff lead, not just attend, community development services, with hours and purpose recorded.
- Offer flexible or innovative products and track their results for LMI and small-business customers.
Steps To Move Up A Rating
- 1Read your latest public performance evaluation and list each weakness the examiners noted.
- 2Compare your lending geography and borrower mix with peers and demographics each quarter.
- 3Set yearly targets for community development loans, investments and service hours, with an owner for each.
- 4Document everything in one CRA file so examiners can see the activity and its community purpose.
- 5Review progress with the board before the next exam cycle and adjust where results lag.
General guidance drawn from patterns in public CRA performance evaluations. It is not a guarantee of any rating; examiners weigh each bank's performance context, assessment area and community needs.
Safety-and-soundness exam results (including confidential regulatory ratings) are confidential supervisory information. BluePen never shows or estimates them.
Talk Track
How are funding concentrations and liquidity needs managed as loan-to-deposit runs above peers?
Recommendation
Review the contingency funding plan and liquidity stress testing against current loan growth.
Built from public FDIC/FFIEC/OCC/Federal Reserve data; not an exam finding or rating.